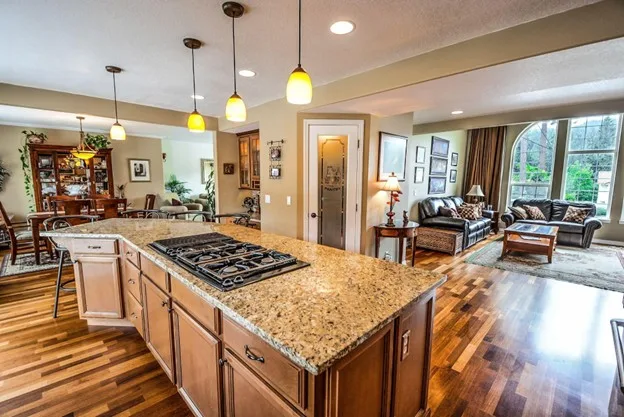
Type your salary into an online mortgage calculator, and the number on the screen can send you straight to listings with bigger kitchens and sprawling gardens.
But a basic calculator does not know your life. It takes a few inputs, applies a formula, and estimates how much you could theoretically borrow. It does not account for weekend trips, plans to start a family, or the business you want to build.
The amount you can borrow and the amount you can comfortably spend are different questions. A useful home-buying budget answers both.
How Lenders Evaluate Affordability
Lenders evaluate risk. They want to know whether your income can support a mortgage alongside your existing obligations. Three factors play a central role.
Your Debt-to-Income Ratio
Your debt-to-income ratio, or DTI, is a lender's most critical affordability metric. It measures the percentage of your gross monthly income that goes toward debt payments, including credit card minimums, car loans, student loans, and your projected mortgage.
Most lenders prefer a DTI of 43% or lower. With gross monthly income of $6,350, that means keeping total monthly debt payments under approximately $2,730.
Your Income Stability
Lenders consider not just how much you earn, but how consistently you earn it. They generally want a solid, continuous employment history spanning at least two years.
If commissions, bonuses, or freelance work make up a substantial part of your earnings, lenders average that income over a longer period to evaluate its reliability.
Your Credit Score
Your credit score reflects your history of managing financial obligations. A high score signals that you pay bills on time and handle debt responsibly.
It also heavily influences your interest rate. A better rate lowers the monthly payment, increasing the amount you can borrow for that payment.
What the Numbers Do Not Know About Your Life
A lender's calculation uses gross income before taxes. It does not build a budget around your personal spending habits. That part is yours to work through.
The Lifestyle You Want to Keep
Dining out, fitness classes, hobbies, and travel all need room in your budget if you want to continue them.
A basic calculator does not reserve money for those choices. Treating its maximum as your spending limit effectively assumes you are willing to sacrifice nonessential spending for the house.
Your Job and Industry
If your industry is volatile, or layoffs and fluctuating hours are realistic concerns, taking the maximum mortgage is risky. A more conservative budget leaves more breathing room.
Someone in a secure public-sector position with guaranteed annual raises might feel more comfortable stretching slightly. The question is how dependable your income feels beyond what appears on paper.
Your Future Goals
Buying a home does not pause the rest of your life. Early retirement, a wedding, a business, or starting a family still needs funding.
Children can change the budget substantially. Childcare alone can rival a mortgage payment. Leave room for the goals you already know matter to you.
A Calculator Budget Versus a Comfortable Budget
Consider the illustrative example of Sarah and James. Together, they earn $101,600 annually before taxes, have excellent credit, and carry minimal debt.
An online calculator estimates they can afford a $571,500 house, with a monthly mortgage payment of roughly $3,050. They begin shopping as though that estimate were an approved amount. In this example, their finances qualify on paper.
Their household budget tells a different story:
- After taxes, 401(k) contributions, and student loan deductions, take-home pay is about $5,840 monthly.
- A $3,050 mortgage leaves $2,790 for everything else.
- After groceries, utilities, vehicle costs, and basic savings, less than $255 remains for entertainment, clothing, or emergencies.
That is what being house poor looks like. In this scenario, a broken furnace or new tires would push them into debt.
Instead, Sarah and James choose a comfortable purchase budget of $412,750. Their illustrative monthly payment falls to $2,160. They still find a lovely home while preserving their lifestyle and peace of mind.
The point is not to adopt their price range. It is to compare the payment with the money you actually bring home.
Include the Costs Beyond the Mortgage
Comparing rent directly with a mortgage payment misses an important difference. Rent serves as the ceiling for the housing payment in the original comparison, while a mortgage is only the starting point for ownership expenses. As an owner, you absorb the additional costs.
Maintenance and Repairs
In a rental, a leaking roof or broken landlord-provided washing machine is the landlord's responsibility. In your own home, those bills belong to you.
A general budgeting rule is to set aside at least 1% of the home's value each year for routine maintenance. Make that allowance part of your budget rather than treating every repair as a surprise.
Utilities and Property Taxes
Moving from a small apartment to a larger house means budgeting for higher utilities. Heating and cooling more space requires more energy.
Check the property's tax assessment and associated tax expense, too. Property taxes can add a significant monthly cost, and basic calculators may not capture that cost accurately.
Furniture and Equipment
A larger home requires more furniture. You may also need a lawnmower, garden tools, or appliances supplied in your previous rental.
Those upfront purchases can drain savings quickly during the first year of ownership. Include them in your planning before you fall in love with a house.
Build Your Budget From Take-Home Pay
Instead of starting with the largest loan offered, work backward from your everyday finances.
- Find your actual take-home pay. Use what reaches your bank account after taxes, retirement contributions, and other deductions, not your gross salary.
- List your nonhousing expenses. Include groceries, transportation, debt payments, subscriptions, entertainment, and your other regular spending.
- Set monthly savings goals. Decide what you want to reserve for emergencies, vacations, and investments.
- Calculate what remains. Subtract expenses and savings goals from take-home pay. Treat the remainder as your maximum comfortable housing budget, not automatically your mortgage payment.
- Reserve money for ownership costs. Account for utilities and subtract estimated property taxes, homeowners insurance, and a monthly maintenance allowance. Keep these amounts separate from the mortgage portion of your worksheet.
The amount left gives you a target for the loan payment itself. Now use a mortgage calculator in reverse: start with that payment and estimate the purchase price using the interest rate entered in the calculation.
This puts the calculator in its proper place. It supports your budget rather than setting your priorities.
Choose Breathing Room Over the Maximum
Home buying is emotional. It is easy to fall for a property just beyond your comfort zone, especially when a lender offers more financing than you expected or encourages you to stretch.
But an extra bedroom or larger kitchen is not worth constant financial anxiety. Your home should provide shelter and security, with room in the budget for life outside its walls.
Before you shop, write down your take-home pay, regular expenses, savings goals, and ownership allowances. Then reach out to Ed Parcaut to talk through how your comfortable monthly budget fits your home-buying plans.


